Two things can be true
I use AI every day, and I’m happy to pay for it. I also think the companies building it are priced for a future that cannot arrive.
Those two statements don’t contradict each other. A product can be genuinely great and still be a terrible investment. This post is about the gap between the two.
What an LLM actually is
An important truth
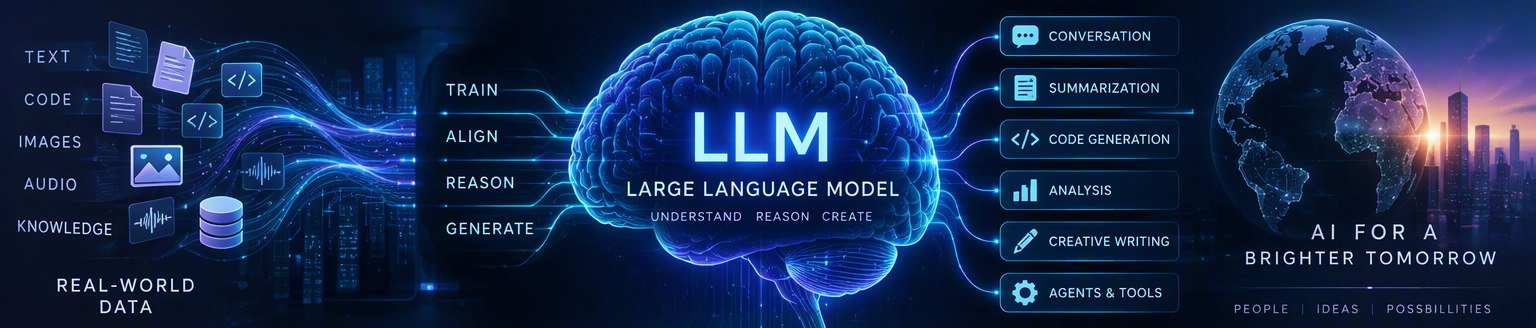
A large language model aka LLM aka modern AI, is not real intelligence. It is a statistical machine trained to do one thing: predict the next word (strictly, the next token) given everything that came before.
Do that well enough, across a large part of the written internet, and you get something that looks a lot like understanding. But underneath, the model has learned which patterns of text tend to follow which other patterns.
That has a direct consequence. When your problem looks like the problems it was trained on, the predictions are excellent. When it doesn’t, the model answers just as confidently, only now it’s guessing with perfect grammar.
Where it shines
Because it’s built on patterns, AI is at its best on tasks it has seen millions of times. And there are a lot of those.
Start with programming. This is genuinely amazing stuff: you describe what you want built, and it builds it. Code is the ideal case for a pattern machine. There’s an enormous amount of it to learn from, it’s highly structured, and you can test whether the output actually works.
The same logic carries over to plenty of other work:
- Financial analysis. Reading statements, summarizing filings, flagging numbers that don’t fit.
- Pattern recognition. Spotting trends and anomalies in logs, data and documents faster than any human.
- Classification. Sorting tickets, emails, invoices and documents into the right buckets.
- Something that resembles creativity. Drafts, names, outlines and ideas. It’s a remix of what it has seen, but often good enough to get you unstuck.
What it’s worth to me
I use AI wherever I can. My time is worth far more than the $20 a month a Claude subscription costs, so paying it is an easy decision.
Would I pay $40? Probably. Would I pay more than $50? I doubt it.
That’s the important part. I’m an enthusiastic, daily user who gets real value out of it, and my willingness to pay still has a ceiling. It’s a great tool, and tools have a price.
Useful is not the same as profitable
The fact that AI does real work, and that I’m willing to pay for it, does not make it a good business to run.
History is full of technologies that changed the world while making their investors poorer. Railroads and airlines transformed how we live, yet much of the value they created went to customers, not shareholders.
AI has the same problem, plus a few of its own:
- The costs never stop. Every new frontier model costs more to train than the last, and every single answer burns compute.
- The competition is brutal. Several well-funded labs and free open-weight models are all chasing the same customers.
- Customers have a ceiling. As above, even fans like me stop at a price that doesn’t come close to covering a trillion-dollar story.
The Anthropic math
To hand a $2 trillion valuation back to shareholders as dividends within 10 years, Anthropic would need to earn roughly $200–325 billion in profit every single year. Here’s how I got there.
Anthropic is preparing to go public, reportedly as soon as mid-November, at a valuation of up to $2 trillion. That would be the largest IPO in history (Yahoo Finance).
Here is where the company actually stands, according to its leaked prospectus and investor updates:
- 2025: about $4.6B in revenue, an operating loss of more than $8B, and a $42B net loss, of which about $34B was an accounting charge tied to earlier fundraising (Reuters via Yahoo Finance).
- Q2 2026: more than $11.5B in revenue, 14 times the same quarter a year earlier, with positive adjusted operating income (TNW).
- 2028 plan: internal projections of $190–200B in annual revenue (Techstrong.ai).
- Commitments: $518B in planned cloud, compute and infrastructure spending in the coming years (Reuters via Yahoo Finance).
The growth is real. But a valuation is a claim on future profits, so let’s test it.
The 10-year dividend test
Imagine buying the whole company for $2 trillion. As an owner, the only way you get paid is through the profits the company hands back to you. Say you want your money back, plus a return, within 10 years. The yearly payout that requires is a standard annuity:
D = V \times \frac{r}{1 - (1 + r)^{-10}}
V is the $2 trillion valuation and r is the yearly return you expect. Dividends come out of after-tax profit, so D is also the minimum net income Anthropic must earn every year for a decade.
| Return you expect | Net profit needed per year | Revenue needed at a 30% net margin |
|---|---|---|
| 0% (just your money back) | $200B | $667B |
| 5.3% (10-year US Treasury yield today) | $263B | $876B |
| 8% (a typical long-run stock return) | $298B | $994B |
| 10% (fair for a risky young company) | $326B | $1.09T |
A 30% net margin is generous: Apple earns about 28% and Microsoft about 40% (ChartRow). The test also assumes Anthropic pays out every dollar, leaving nothing for the $518B of compute it has already committed to.
Now put it in my own terms. At the $50 a month I’d pay at most, a customer brings in $600 a year. The 8% case needs about $1 trillion of revenue a year, or roughly 1.7 billion people paying $50 every month. Most of Anthropic’s revenue comes from businesses, not individuals like me, but the scale is the point.
Compared with the most profitable companies on Earth
At an 8% return, Anthropic would have to earn more than the most profitable company in the world, every year, for ten years straight.
| Company | Net income, trailing 12 months |
|---|---|
| Alphabet | $244B |
| Nvidia | $193B |
| Amazon | $135B |
| Microsoft | $134B |
| Apple | $129B |
| Berkshire Hathaway | $86B |
| Micron | $85B |
| Meta | $68B |
| JPMorgan Chase | $65B |
| Anthropic (2025) | −$42B (net loss) |
| Anthropic needs, at a 0% return | $200B a year |
| Anthropic needs, at an 8% return | $298B a year |
Sources: ChartRow as of Oct 12, 2026; Anthropic’s 2025 figure from its prospectus via Reuters; required profit from the 10-year test above. Anthropic’s 2025 loss includes about $34B of accounting charges tied to earlier fundraising.
Even the zero-return case, just getting your $2 trillion back, means out-earning Nvidia, today’s second most profitable company. And those companies took decades to get there; Anthropic would have to do it starting from a loss. One caveat: trailing net income includes one-off items such as investment gains, so some of these figures run hot.
A hazard, not an investment
Meeting a $2 trillion valuation looks impossible to me. Even a modest version of the test asks Anthropic to out-earn the most profitable company on Earth, every year for a decade, starting from a company that lost money last year.
The bull case says I’m being too strict. Markets price companies on decades of profits, not ten years, and at Microsoft’s price-to-earnings ratio of about 30, $2 trillion “only” needs around $67B a year in profit. Fair enough. But that still means Anthropic must become one of the ten most profitable companies in the world, keep fat margins while rivals cut prices, and stay ahead in a race where last year’s model is already obsolete.
When a price only works if everything goes right, buying in isn’t investing. It’s a hazard.
AI is a great tool, and I’ll keep paying for it. I just won’t be paying for the stock.
This is my opinion, not financial advice.
Sources
- Anthropic reportedly looking to IPO as early as mid-November, Yahoo Finance, Oct 1, 2026
- Anthropic’s IPO prospectus shows sweeping AI vision, surging costs, Reuters via Yahoo Finance, Sep 29, 2026
- Anthropic’s quarterly revenue passed $11.5bn, up more than 14-fold, TNW, Aug 15, 2026
- Anthropic revenue surges to $65 billion run rate ahead of expected fall IPO, Techstrong.ai, Aug 17, 2026
- Most profitable companies (2026), ChartRow, data as of Oct 12, 2026